

Condo and strata documents can change the mortgage path
Reserve funds, bylaws, insurance, and building condition can all matter when a lender reviews a New Westminster condo. The cleaner the document review, the fewer surprises later.
Pragmatic Mortgage Lending · BC
New Westminster moves quickly and the details matter. Whether you are buying a condo near the riverfront, moving up from Queensborough, or deciding whether to renew, switch, or refinance before the bank’s default offer gets expensive, we help you map the real cash needed to close and choose a mortgage that fits the property, payment, and next chapter.
Serving New Westminster with phone and virtual appointments. Office details →

New Westminster mortgage options
Get the budget, cash-to-close number, and strata-aware lender fit right before the search gets emotional.
Plan a condo purchase 02Coordinate sale proceeds, deposit timing, and bridge needs so the mortgage keeps pace with the move.
Plan a move-up purchase 03Compare the bank’s offer against better options before convenience turns into the most expensive decision.
Review renewal options 04Model payment relief, penalty cost, and equity access before you break the current mortgage.
Review refinance options 05If you need to buy before the sale lands, the timing and lender structure need to be clean from the start.
Explore bridge financing 06Set the documentation strategy early so the file is easy to place instead of hard to explain.
Review self-employed optionsThe place matters
The useful questions here are usually about strata, timing, cash-to-close, and whether the mortgage still makes sense once the full move is mapped out.
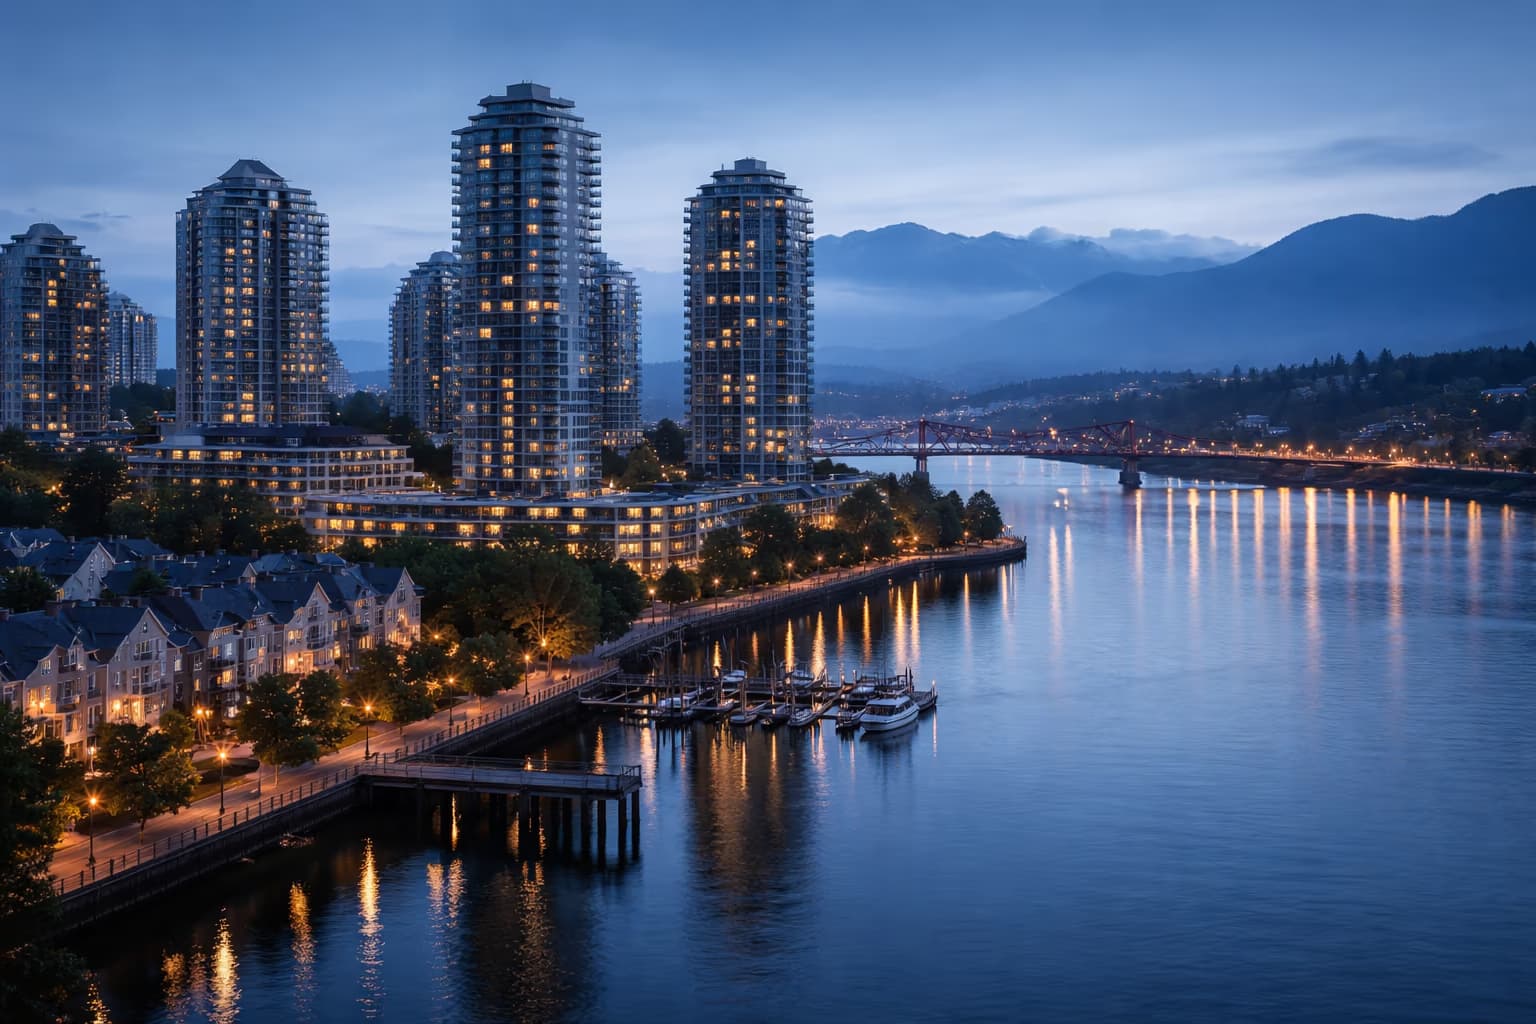
Reserve funds, bylaws, insurance, and building condition can all matter when a lender reviews a New Westminster condo. The cleaner the document review, the fewer surprises later.
If the sale side and purchase side are close together, we plan the cash flow, conditions, and bridge structure so you are not improvising under deadline pressure.
A renewal letter is convenient, not necessarily competitive. We compare staying, switching, and restructuring before the easiest path becomes the most expensive one.
If you want lower payments, debt consolidation, or equity access, the math should include penalty cost, long-term interest, and whether the new structure actually improves your position.
The better move is to sort the income story before the file is live. That keeps the lender fit broader and the process calmer.
A full mortgage practice
Buy with a clear budget, BC closing-cost plan, and lender fit that matches the property and timeline.
Use this path when you want a purchase file that stays clean from pre-approval through possession and does not leave you guessing at offer time.
Know the real budget and cash-to-close picture before you commit to a listing.
Start with the numbers and the document path so the first purchase feels deliberate instead of rushed.
Compare the bank offer against better options before convenience becomes the expensive default.
Renewal is often the cleanest time to compare staying, switching, and restructuring without adding friction to the file.
Review payment relief, equity access, and total cost before you make a break decision.
If the goal is cash flow, debt cleanup, or equity access, the structure needs to solve the real problem instead of creating a new one.
Keep the sale-and-purchase gap organized and financeable.
Bridge planning matters when closing dates do not line up and you need a clean answer before possession pressure arrives.
Use the right documentation strategy from day one when income is variable or complex.
Set the lender path early so the file is easier to underwrite and the process stays calmer.
Use the secure form, a call, or a virtual consult. We’ll keep the next step practical, fast, and anchored in the file in front of you.
Licensed Mortgage Broker
Dinah keeps purchase, renewal, and refinance planning grounded in real numbers and clear trade-offs.
Licensed Mortgage Broker
Jessica is known for fast follow-through, clean communication, and mortgage advice that stays practical under deadline pressure.
Mortgage Broker
Mack helps buyers and homeowners stay organized through the file while keeping the lender strategy aligned with the bigger goal.
Nearest advisory studio
The Surrey Advisory Studio is the nearest verified office for New Westminster borrowers. Use it as the nearby consult base for phone, form, or video support.
Not sure who to choose? Tell us what you are planning and we will connect you with the right person for the file.
Start a conversation
Tell us what you want to do and when. We’ll help you understand the next step, the documents needed and the choices worth comparing.
We’ll review your goal, the property type, and the timing before we suggest the next step.
Prefer to book a time? ↗See broker compensation and fees. Verify licensing through BCFSA public registry.
Clear answers
Because the right mortgage is not always the easiest one to find. A broker helps you compare lenders, explain the trade-offs clearly, and choose the option that fits the property, the payment, and the bigger plan.
Plan for legal fees, inspection costs, appraisal when needed, moving costs, and any strata-related adjustments. The better move is to model the full cash-to-close number early.
Yes. Reserve funds, bylaws, insurance, and building condition can all affect lender fit and the ownership cost, especially in condo-heavy areas.
Yes. Renewal is often the best time to compare. Sometimes staying is fine. Sometimes switching or restructuring is better. The key is to compare before you sign.
Yes. The main difference is documentation and lender fit. When the income story is clean early, the file is usually easier to place.
When you need the purchase to move before the sale closes and you want a structured plan for the gap. Timing, risk, and carrying cost need to be clear before you rely on it.
Pragmatic Mortgage Lending · BC & Alberta
Purchase, renewal, refinance or a more complex mortgage: our team helps you compare the possibilities for your New Westminster home.