Downsizing should be about comfort, not just debt size
A smaller mortgage is useful only if the new home actually fits the way you want to live. We build around the lifestyle change, not the loan size alone.
BC mortgage brokerage
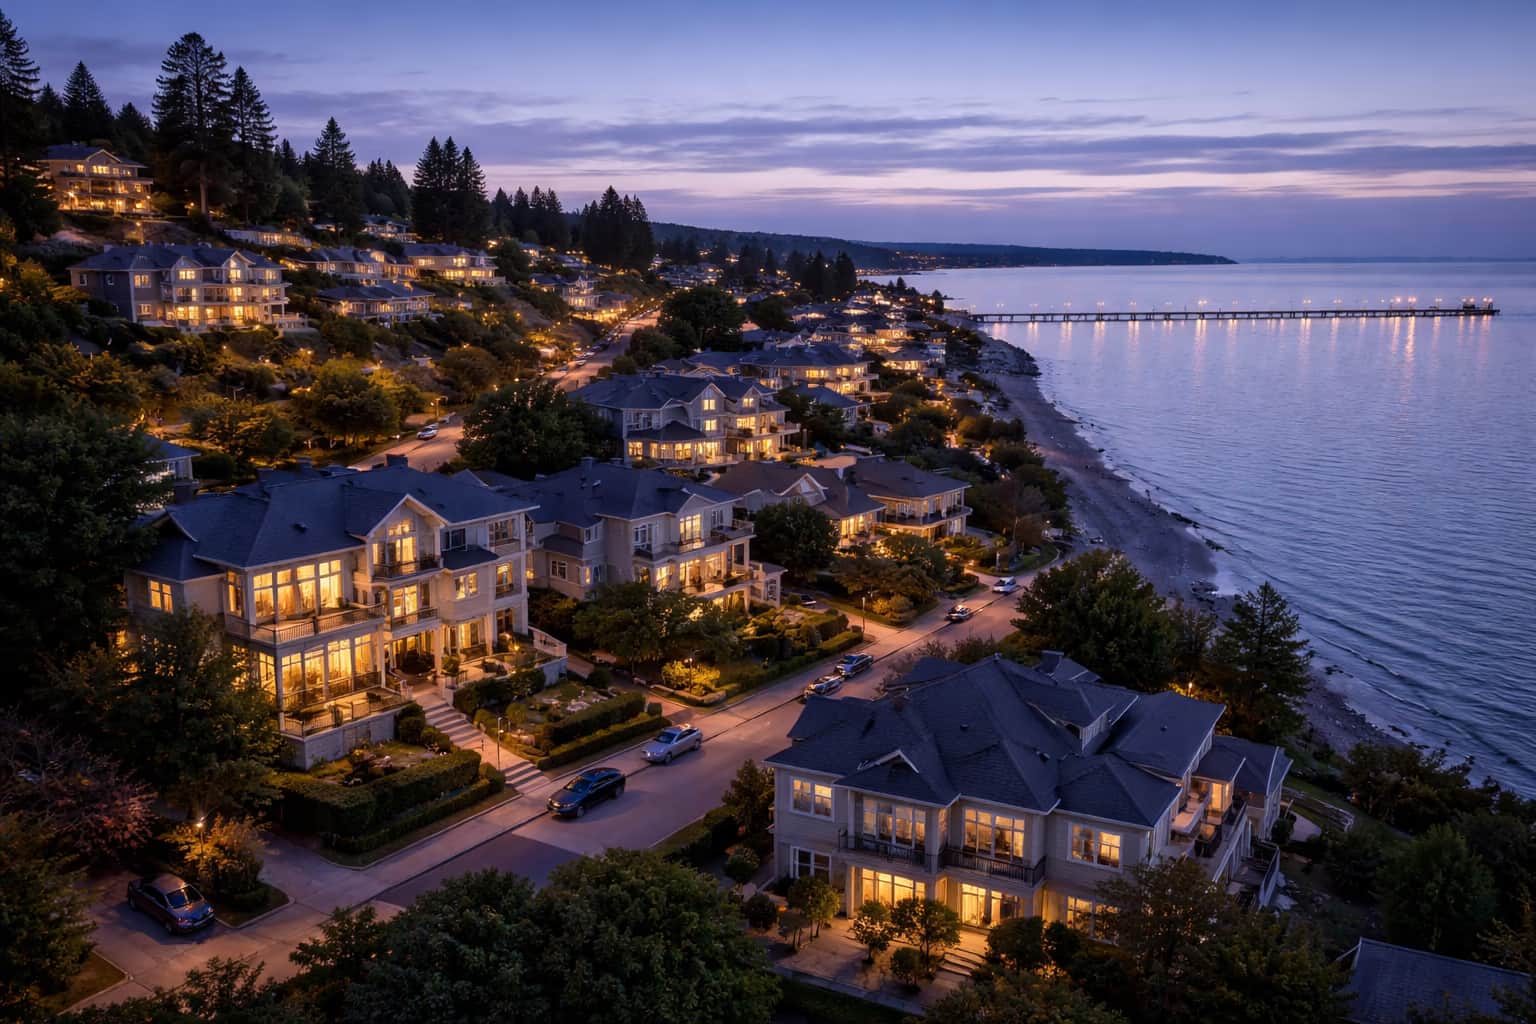
White Rock often rewards a calmer, more practical mortgage conversation. If you are downsizing, right-sizing, renewing, refinancing, or buying a coastal condo or smaller home that fits how you want to live now, we help you compare lenders, understand the closing costs, and choose a structure that supports cash flow, comfort, and flexibility rather than just borrowing as much as possible.
Meet by phone or video for a property in White Rock, or visit our Surrey office by appointment.
White Rock mortgage options
Build the mortgage around comfort, cash flow, and the way you want to live next.
Plan a downsizing moveGet the budget, strata review, and closing-cost plan right before the search gets emotional.
Plan a purchaseCompare the bank’s offer against better options before convenience becomes the expensive default.
Review renewal optionsRun the penalty, payment, and flexibility math before you change the structure.
Review refinance optionsIf the current home needs to sell before the next one closes, plan the gap early.
Explore bridge financingBuild the lender story early so the file is easier to place.
Review self-employed optionsThe place matters
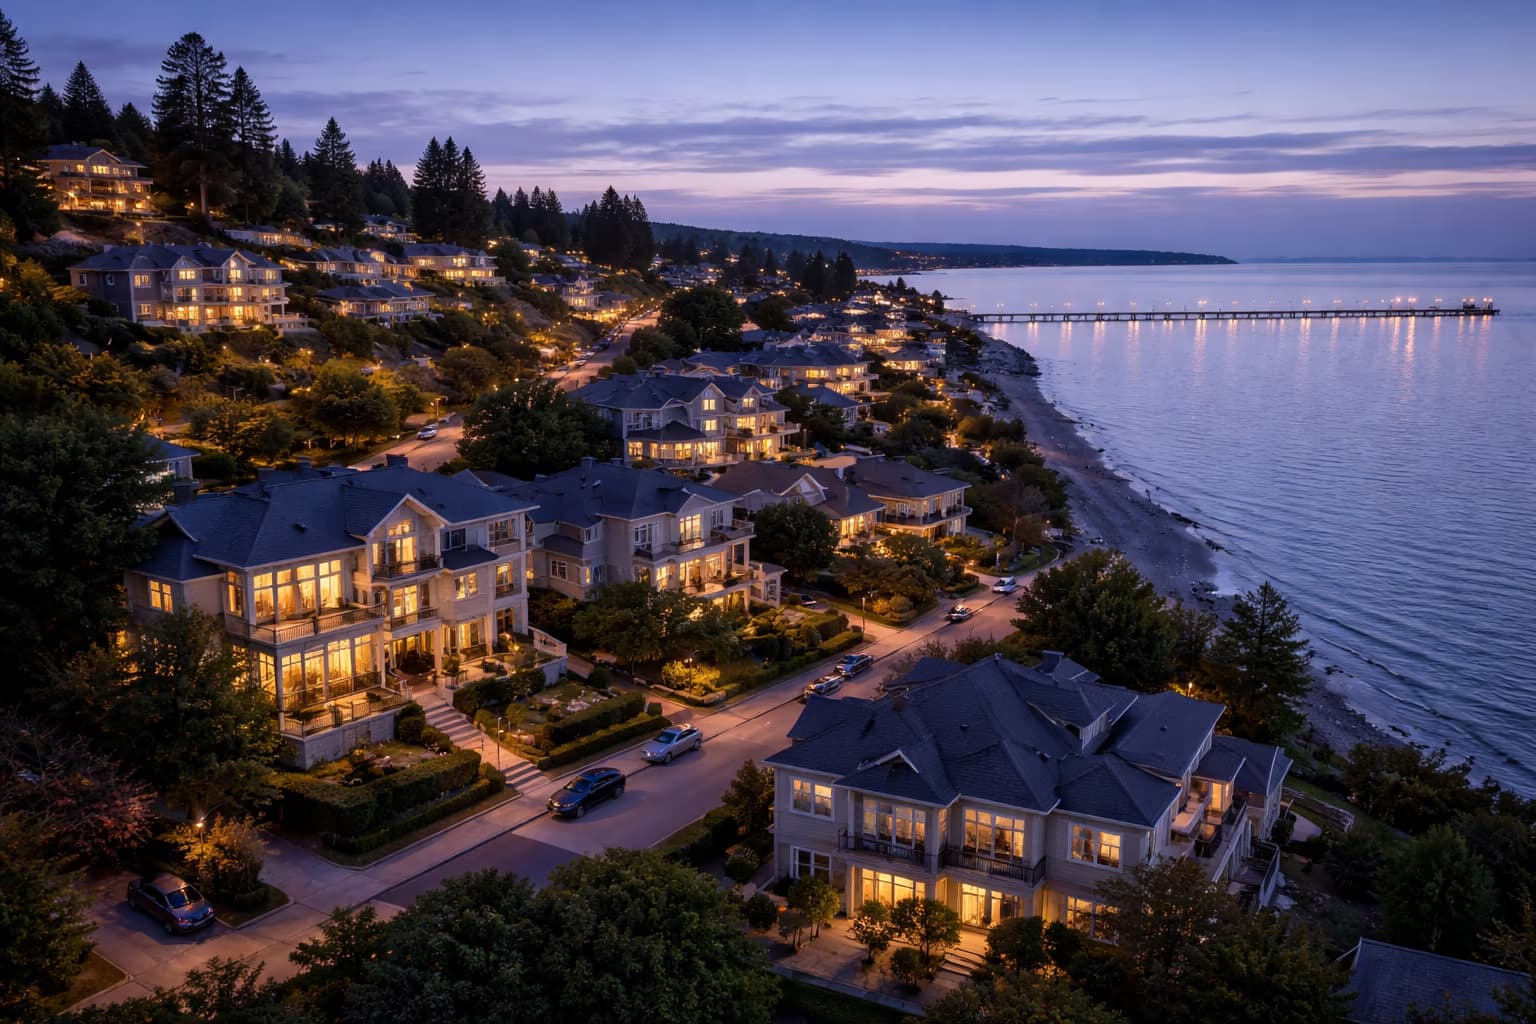
The important questions here are usually about cash flow, closing costs, the condo or strata details, and whether the mortgage supports the next chapter instead of just the biggest number.
A smaller mortgage is useful only if the new home actually fits the way you want to live. We build around the lifestyle change, not the loan size alone.
Insurance, strata fees, bylaws, and building condition can all affect lender comfort and ownership cost.
If you need to sell before you buy, or buy before you sell, the timeline and carrying cost should be clear early.
We compare rate, term, penalty exposure, and prepayment room so the next chapter stays easy to live with.
If the mortgage is part of retirement or a more predictable monthly plan, the payment and flexibility matter more than an aggressive approval number.
A full mortgage practice
Buy with a clear budget, lender fit, and cash plan that matches the property.
Use this path when you want a purchase file that feels calm, readable, and aligned with the life you want next.
Know the real budget and cash-to-close picture before you commit to a listing.
Start with the numbers and the document path so the first purchase feels deliberate instead of rushed.
Compare the bank offer against better options before signing.
Renewal is often the cleanest time to compare staying, switching, and restructuring without adding friction to the file.
Review payment relief, debt consolidation, equity access, and total cost before you make a break decision.
If the goal is cash flow, debt cleanup, or equity access, the structure needs to solve the real problem instead of creating a new one.
Keep the sale-and-purchase gap organized and financeable.
Bridge planning matters when closing dates do not line up and you need a clean answer before possession pressure arrives.
Use the right documentation strategy from day one when income is variable or complex.
Set the lender path early so the file is easier to underwrite and the process stays calmer.
Use the secure form, a call, or a virtual consult. We’ll keep the next step practical, fast, and anchored in the file in front of you.
Licensed Mortgage Broker
Licensed Mortgage Broker
Mortgage Broker
Nearest advisory studio
The Surrey Advisory Studio is the nearest verified office for White Rock borrowers. Use it as the nearby consult base for phone, form, or video support.
Not sure who to choose? Tell us what you are planning and we will connect you with the right person for the file.
Start a conversation
Tell us what you want to do and when. We’ll help you understand the next step, the documents needed and the choices worth comparing.
We’ll review the property type, the cash-flow target, and the timing before we suggest the next step.
Buying outside BC? Ask what options are available for your property.
Prefer to book a time? ↗See broker compensation and fees. Verify licensing through BCFSA public registry.
Mortgage questions
Because the right mortgage is not always the easiest one to find. A broker helps compare lenders, explain the trade-offs, and keep the budget, property, and timing aligned.
Both. The mortgage should support cash flow, comfort, and the way you want to live next, not just the loan size.
Yes. Strata fees, bylaws, insurance, and building condition can all affect lender fit and the ownership cost.
When you need to sell one property and buy another on different timelines and want a structured plan for the gap.
Yes. Renewal is often the best time to compare. Sometimes staying is fine. Sometimes switching or restructuring is better. The key is to compare before you sign.
Yes. The key is the right lender path and a clean documentation story from the start.